14 Sept 2026 · Ecosystem · All pharmacies · Owner
A suite for the pharmacy, not one more tool
19,943 pharmacies open in France, 19,942 different companies. None can build alone what each would benefit from having. That is the problem a suite solves — and it is not the same problem a tool solves.
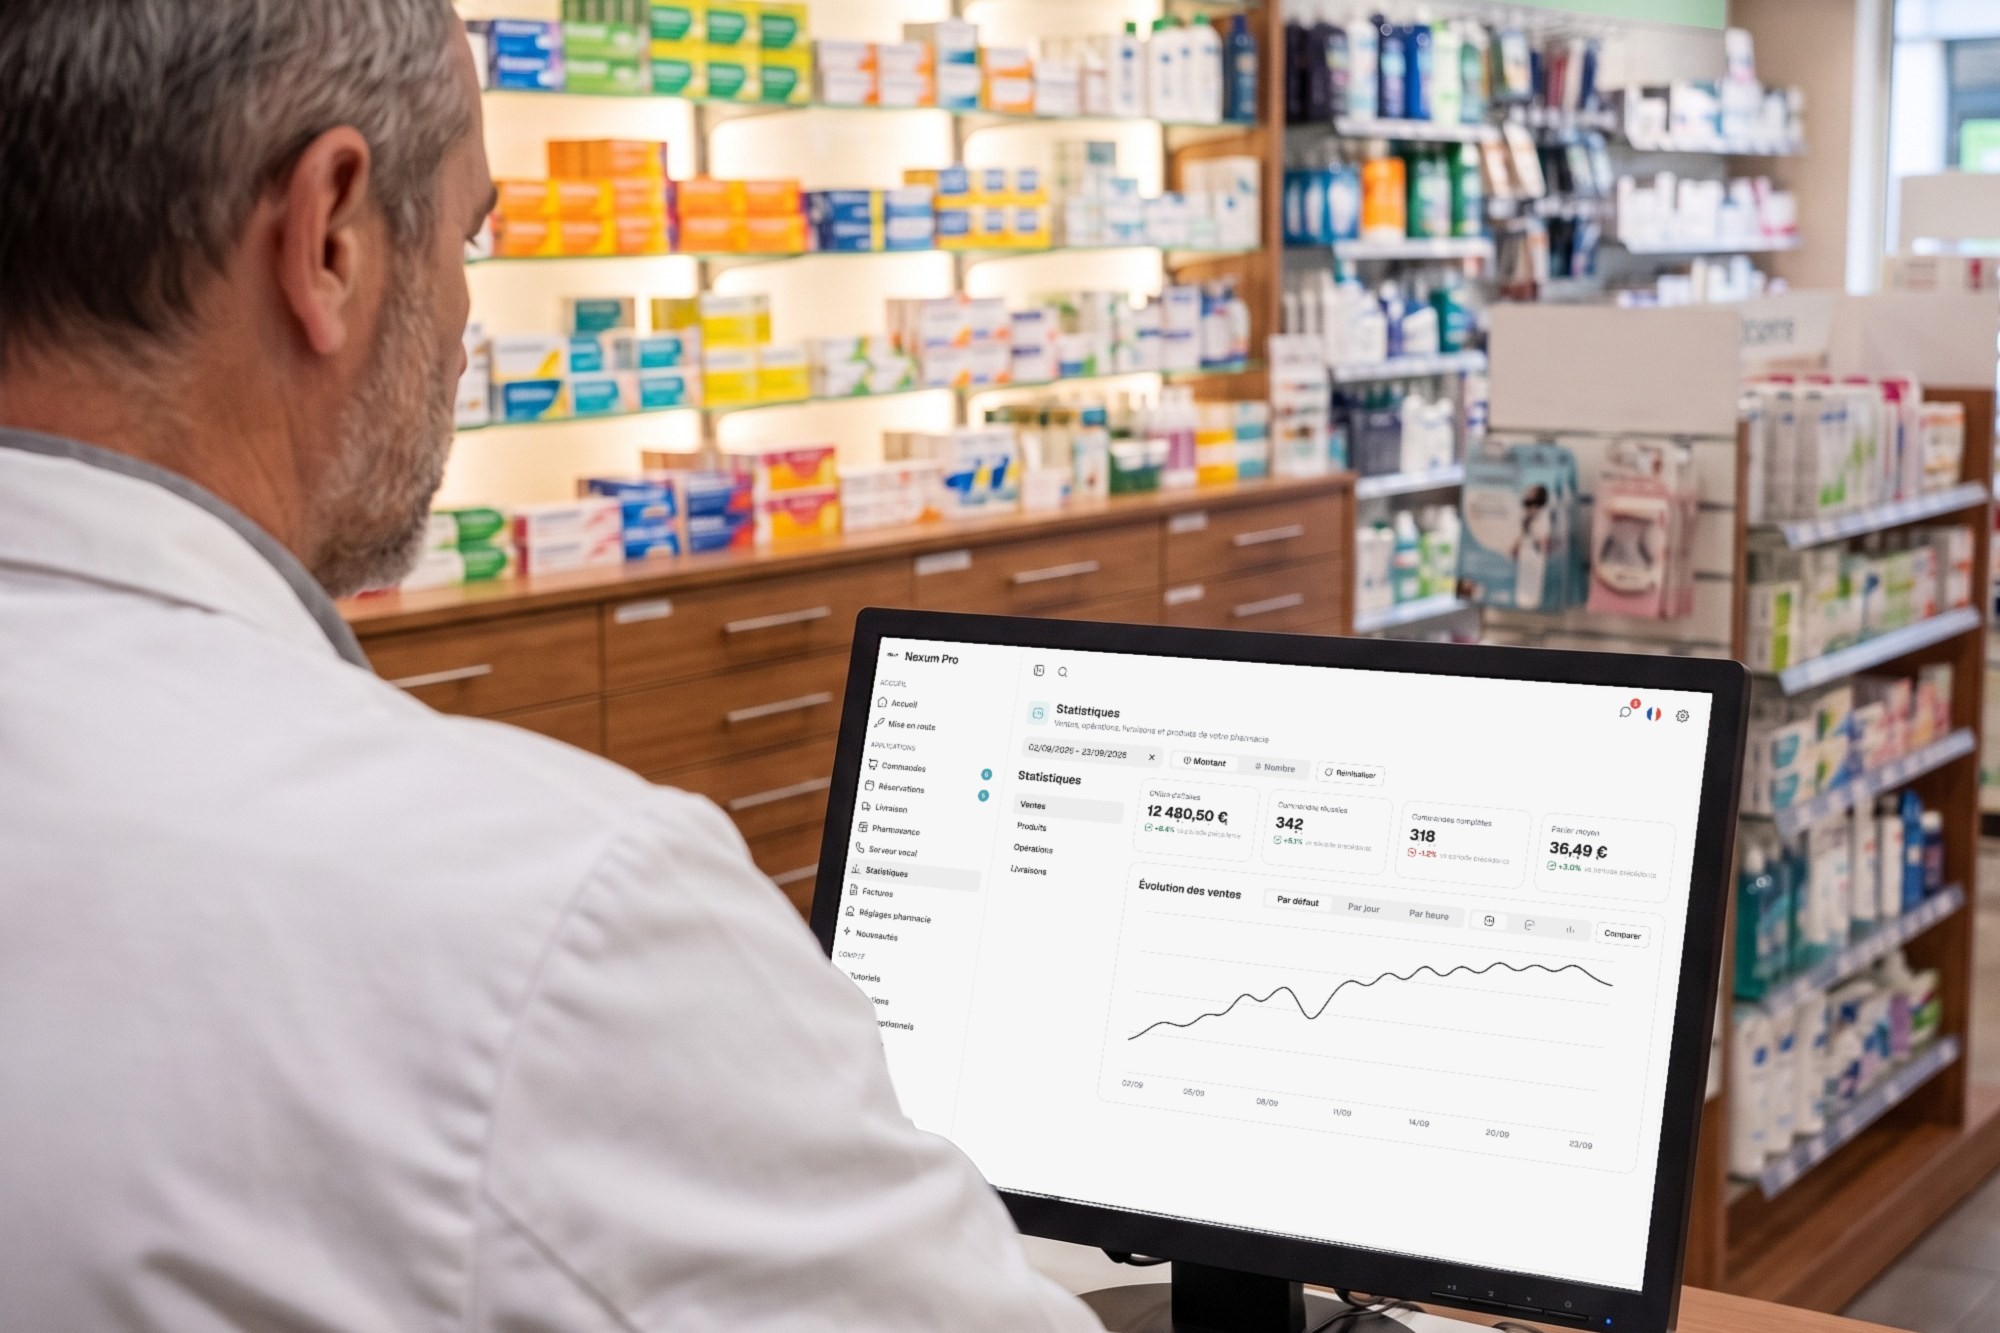
A pharmacy owner looking to equip the pharmacy easily finds a tool for every problem: a voice agent for the telephone, a diary for appointments, an online shop for e-commerce, a delivery app. Each does properly what it is sold for.
So the question is not whether these tools exist. It is why, once installed, the pharmacy still feels it is re-entering the same information three times.
1. One pharmacy, one company
The starting point is a measured fact. The FINESS feed of the Agence du numérique en santé, as of 1 August 2026, lists 19,943 pharmacies open in France — held by 19,942 distinct legal entities.
In other words: there are no pharmacy chains in France. The banners one comes across are commercial pharmacy groups, not single companies operating several pharmacies. One pharmacy, one company, one owner who decides and who pays.
The consequence is direct. In a sector where a few groups operate hundreds of outlets, software is built in-house and amortised across the network. Here, each pharmacy is a ten-person SME that has to buy its IT on its own.
2. What the French pharmacy does not have yet
The same campaign catalogued, site by site, the online presence of European pharmacies. In France, 949 pharmacy websites were identified, of which 763 linked to a pharmacy by evidence stated on the page — a SIRET or a FINESS number; the name alone is never evidence. That makes less than 4% of pharmacies with an identified e-commerce presence: a floor, not a total, because a null value here means “nobody has looked”, never “no”.
A second figure says the same thing differently. Of these 19,943 establishments, the official register records one e-mail address and zero websites. The State knows exactly where each pharmacy is, who runs it and since when — and knows nothing of its digital presence.
The European comparison completes the picture: 19 French websites advertise a WhatsApp contact, against 486 in Germany; 12 advertise a mobile app, against 437. Conversely, 182 advertise teleconsultation against 16. The reading is not an indictment — the German model sells purchasing convenience, the French one sells the health service. The French pharmacy did not miss the digital turn out of negligence: it invested in its profession. But the channels through which its customers reach it have changed.
3. The alternative is called stacking
We recorded the public prices of 22 players, from 24 sources dated 2 September 2026: general-purpose and healthcare-specific voice agents, human telephone answering services, appointment platforms, online shop publishers, delivery channels, neighbouring pharmacy tools.
The survey gives three ways to equip a pharmacy, and the cheapest deserves to be stated frankly: an entry-level assembly costs less than our complete offer. That is true on paper, and it would be dishonest to hide it. What that price does not say fits in four numbers: five contracts, five invoices, five support desks, zero native bridge.
None of these families covers the twelve needs of a pharmacy. General-purpose voice agents are billed by the minute and read no pharmacy management software: they can say they will check, not that three boxes are left. Appointment platforms do not answer the telephone. Online shops sell the shop window, not the delivery. Delivery channels take a commission and keep the customer relationship.
Each does its job. None talks to the next.
4. Why separate building blocks are not enough
Take the most ordinary case: a customer calls to find out whether a product is available.
With a generic voice agent, they get a polite answer and an invitation to call back, or a transfer to the counter — that is, the very interruption one was trying to avoid. With an agent that reads the real stock, they get a firm answer. But if they want to book, something has to record the booking. If they want to pay, something has to take the payment — and only take it at collection, otherwise the owner refunds the customers who do not turn up. If they want delivery, a courier has to be dispatched — but not immediately, otherwise the courier waits during preparation.
Each link depends on the previous one. An off-the-shelf voice assistant would not have known how to query a stock; a generic engine would not have handled an approximate pronunciation over the telephone. Both were written by the same team, to answer each other. That chaining is what distinguishes an ecosystem from a software suite: not the number of features, but the fact that each one pours its result into the next.
5. The building block the customer will never see
There is one building block nobody talks about, and it is the only one that makes the others true.
Reading a pharmacy’s stock means talking to the management software it already uses — the one its team works on, the one it has no reason to change. That layer, we wrote first. It centralises, so that a single connection is enough whatever the software; it works in read and write, which removes double entry; it knows the state of the pharmacy and not only that of the shelf — open, able to prepare and to serve; and it states the freshness of the data, because knowing when a piece of information was read is information in itself.
It explains why the rest holds: a true catalogue makes a shop window credible, a verified availability makes a delivery time achievable, a queryable stock makes a voice assistant useful rather than polite. Nobody sells this layer, and nobody will: it only has value for whoever builds on top of it. It had to be written, or everything else given up.
One detail will say the rest. The price a customer sees includes the dispensing fee; our connection isolates it from the selling price, exactly as the owner’s software does. That is no technical feat: it is the difference between a tool written for pharmacies and a tool written for shops.
6. What it changes, concretely
A suite is not judged by the length of its catalogue, but by what no longer needs doing. A promotion entered once is propagated everywhere. An uploaded prescription becomes a list of products the team checks and validates, instead of retyping it. An order taken by telephone at 11 pm exists on the same screen as the one that came through the app or a platform. Invoice, accounting export and payout are in the same place as everything else.
And the channel through which the customer comes in stops mattering. A conversation, a call, a booking and an order are the same object seen from four angles. The team works on a single screen, not seven.
7. And what it does not solve
A suite is not an answer to everything, and it is better to say so than to let people find out.
It does not replace the pharmacist. What is automated is the data entry — never the decision. Dispensing remains entirely in the hands of the pharmacy owner, automatic checks add to their judgement without replacing it, and responsibility does not move.
It does not remove the need to choose where to start. For most pharmacies the telephone is the first pain and therefore the first door; but it is a door, not the house.
And it has its work in progress, which we display rather than keep quiet: real-time availability is in production ; orders between fellow pharmacies of the same network are deployed at a first pharmacy group and not yet generalised; complete ordering via instant messaging awaits a validation that does not depend on us.
The rest — what is available, what is not, and why — is written on the product pages, feature by feature, with its status.
Market data sources: FINESS feed finess-structures of the Agence du numérique en santé, 1 August 2026 (19,943 pharmacies open, 19,942 legal entities, 1 e-mail address and 0 websites in the register); site-by-site measurement campaign, 8,379 websites catalogued in 16 countries, France 949 websites of which 763 linked by evidence. Competitive survey: 22 players, 24 public sources dated 2 September 2026. A website is only linked to a pharmacy on evidence stated by the page itself; a null value means "nobody has looked", never "no". Equipped base: .
Let's see what Nexum would change in the pharmacy
A demonstration led by a pharmacist from the team, on the pharmacy's own call and order flows.